Se abre en una pestaña nueva

95.75 MWp Brazilian Solar PV Portfolio

País
BrasilBrasil
ID del anuncio
L#20261152
Precio objetivo
$97,200,000
Ingresos
$28,850,000
EBITDA
$27,170,000

Descripción

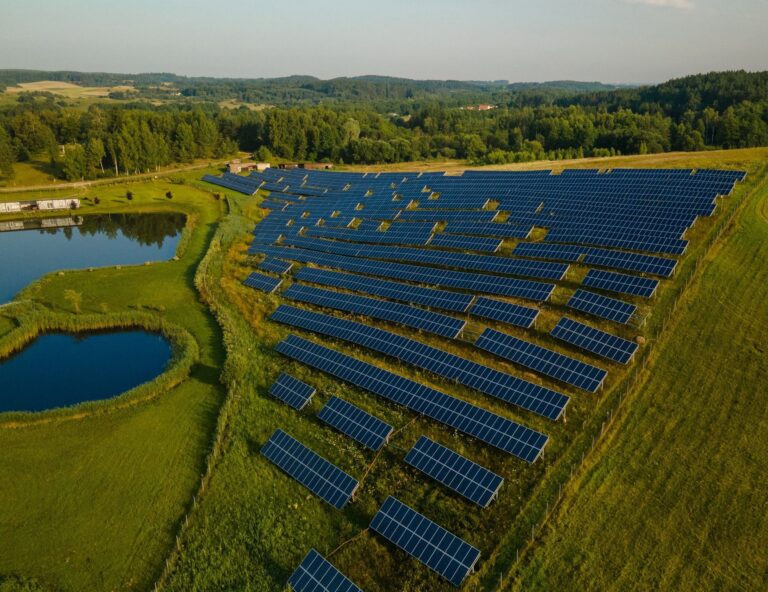
Project Alfa is a utility-scale solar photovoltaic (PV) aggregation platform in Brazil consisting of 67 solar plants strategically positioned across 10 Brazilian states. The platform represents a total declared capacity of 227.16 MWp with an estimated recurring generation profile of 497,480 MWh/year. The asset portfolio is structured around a dual-monetization commercial strategy: contracted/wholesale electricity sales coupled with upside potential from verified carbon emission reductions (298,488 $\text{tCO}_2$/year). Total documented capital expenditure is US$152.8 million, reflecting an entry cost basis of US$0.67 million/MWp.

Investment Highlights Phase 1.

Metric Original USD Equivalent
Portfolio Capacity 95.75 MWac 95.75 MWac
Installed DC Capacity 124.48 MWp 124.48 MWp
Plants 33 33 Plants
SPVs 28 28 SPVs
Full EPC CAPEX R$497.9M ~US$96.7M
Contracted Revenue over 10 Years R$1.61B ~US$312.6M
Unlevered Project IRR 26.1% 26.1%

Portfolio Overview

State Plants MWac MWp Share
Bahia 25 78.25 101.73 81.7%
Pernambuco 8 17.50 22.75 18.3%
Total 33 95.75 124.48 100%

CONTRACTED REVENUE MODEL

The investment case is underpinned by contracted revenue rather than merchant power-price exposure during the initial PPA period.

PPA Structure

  1. 01
    Contracted priceUS$126.95/MWh
  2. 02
    Initial term10 years under a 5+5 structure
  3. 03
    Indexation4.5% p.a.
  4. 04
    Year-one generation207,261 MWh
  5. 05
    First full year of revenue2029
  6. 06
    Contracted revenueapproximately US$314.5 million

The PPA price is modelled at a 21.7% premium to the portfolio LCOE, which is estimated at approximately US$104.30/MWh.

DEVELOPMENT & CONSTRUCTION SCHEDULE

Commercial operation is phased between 2026 and 2028, reducing reliance on a single construction milestone.

Year Plants Capacity
2026 9 27.50 MWac
2027 21 58.25 MWac
2028 3 10.00 MWac
Total 33 95.75 MWac

Approximately US$93.4 million of the US$97.2 million total CAPEX is concentrated in 2026–2027.

FINANCIAL PROFILE

Base Case — Unlevered

Metric Base Case
Full EPC CAPEX US$97.2M
Project IRR 26.1% p.a.
NPV @ 14% US$75.6M
Simple Payback 5.5 years
Portfolio LCOE US$104/MWh
EBITDA Margin 92.9%

Regulatory & Investment Disclaimer

This executive summary and the financial projections contained herein are prepared solely for indicative, preliminary informational purposes and do not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation to acquire any securities, investment platform units, or debt instruments.
All financial profiles, return metrics (ROI), Enterprise Values, and payback periods are modeled estimates derived from third-party operational assumptions and base-case operational scenarios. Actual performance may vary materially based on actual solar irradiation, grid curtailment, national transmission connection approvals, wholesale power market (PLD/PPA) volatility, and operational availability.
Carbon Credit Conditionality: Projected carbon-credit revenues of US$8.95M to US$14.92M per annum represent uncontracted financial upside. Receipt of carbon revenues is strictly contingent upon the project platform successfully satisfying all applicable additionality assessments, validation criteria, baseline certifications, third-party independent verifications, and credit issuance protocols administered by international voluntary or compliance carbon registries.
Potential investors must conduct their own independent technical, environmental, tax (Lucro Real vs. regional SUDENE incentives), and legal due diligence before making an investment commitment. No representation or warranty, express or implied, is given as to the achievement or reasonableness of any future projections, estimates, or prospects.
Datos clave

ID del anuncio
L#20261152
País
Brasil
Sector
Energía renovable
Estado de la operación
Disponible
Precio objetivo
$97,200,000
Ingresos
$28,850,000
EBITDA
$27,170,000
Múltiplo de ingresos
3.37x
Múltiplo EBITDA
3.58x

Asesoramiento M&A en el mercado medio – Deal Tombstones 2024

AsesorDeals
MergersCorp M&A International21
Keith Advisory17
GCG9
JP Morgan41
Jefferies23
Lazard26
Goldman Sachs30

Empresas en venta

Oportunidades similares